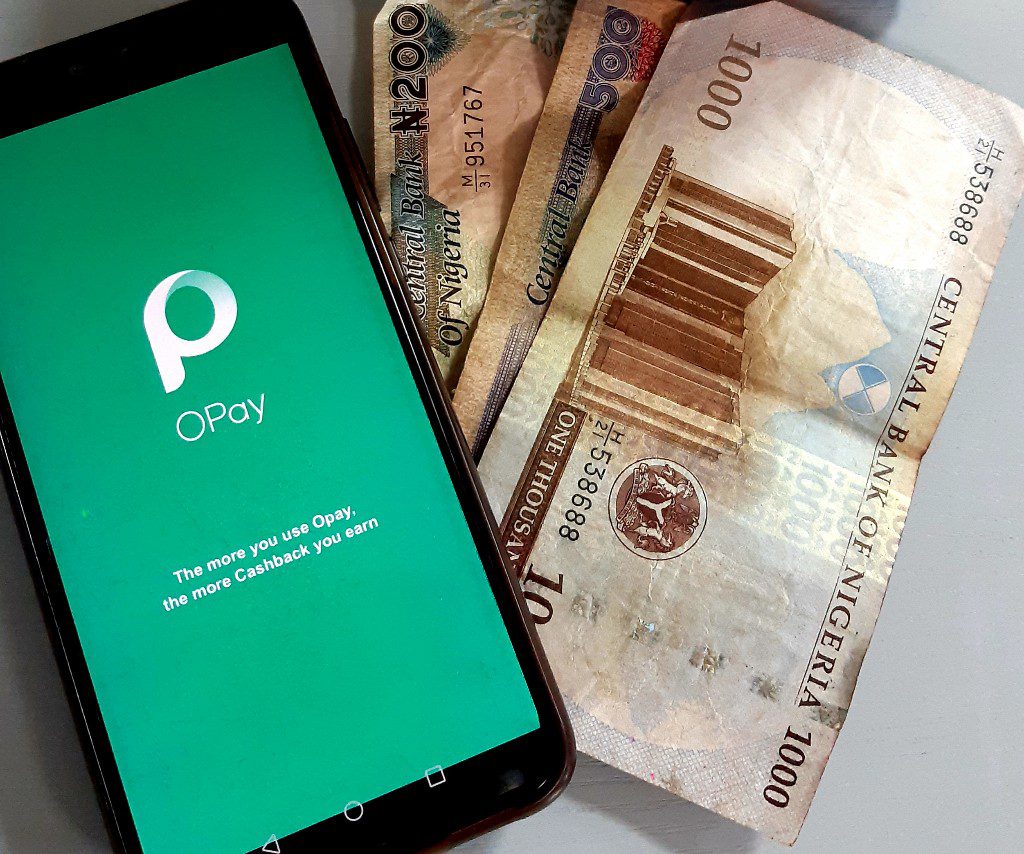
In 2025, Nigeria’s electronic payments ecosystem handled more than ₦1.2 quadrillion (approximately $880.51 billion) in transactions, with fintech firms OPay and Moniepoint accounting for a combined $644.85 billion of that volume.
Transaction volumes and average ticket size
OPay processed 62.3 billion transactions worth $358 billion, while Moniepoint recorded 14 billion transactions valued at ₦412 trillion (about $286.85 billion at the end‑of‑year exchange rate of ₦1,436.31 per dollar). OPay’s transaction count was 4.45 times higher than Moniepoint’s, but Moniepoint’s average transaction value was $20.49, roughly 3.56 times OPay’s $5.75.
Lending activity and revenue
Both companies expanded credit services in 2025. OPay originated $938.3 million in consumer loans, a 284.71 % increase from the previous year, and reported $260.3 million in loan‑financing revenue, representing 48.5 % of its total $536.25 million revenue. OPay’s provision for expected credit losses rose to $121.3 million, 46.6 % of its loan‑financing revenue.
Moniepoint disclosed disbursement of more than ₦1 trillion (about $696.23 million) in business loans, up from $71 million in 2023. The firm does not publish revenue or profit figures, but its transaction value would translate to an estimated $430.28 million in revenue if it achieved OPay’s 0.15 % conversion rate.
OPay’s overall profit before tax stood at $110.79 million, a net margin of roughly 20.66 %. Applying the same margin to Moniepoint’s estimated revenue yields an indicative profit of $88.89 million, though the figure is not reported by the company.
Moniepoint serves over 20 million businesses and individuals and has recently expanded into Kenya, while OPay operates in Indonesia, Egypt and Pakistan but derived 88.1 % of its 2025 revenue from Nigeria.
Regulatory changes introduced by the Central Bank of Nigeria in June 2026 set new caps on market dominance, limiting consumer‑issuing to 25 % of activity and merchant acquiring to 15 %.
Both fintechs continue to convert payment histories into credit intelligence, but OPay focuses on high‑frequency consumer transactions, whereas Moniepoint leverages merchant‑centric data to extend working‑capital loans.
As of the latest disclosures, OPay and Moniepoint remain the dominant players in Nigeria’s fintech landscape, driving the bulk of electronic transaction volume and shaping the country’s digital credit market.
0 Comments
Leave a Comment
No comments yet. Be the first to share your thoughts!